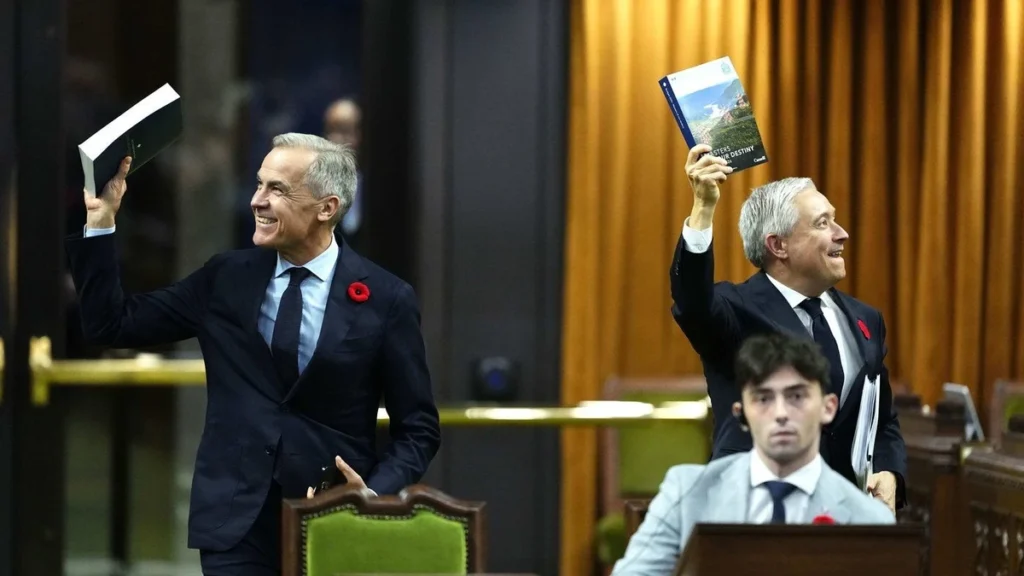
Canada’s self-employed could swap four quarterly tax payments for one. Budget 2026, tabled in Ottawa on 5 November by Finance Minister François-Philippe Champagne, proposes that individuals whose main income comes from a business be allowed to make a single annual tax instalment equal to two-thirds of the year’s combined federal and provincial net tax owing, due by 31 December, starting with the 2028 tax year. The rest would be paid when the return is settled the following spring.
The change sits inside a wider package that the Department of Finance describes as the most ambitious effort in decades to simplify the tax system. For sole traders, consultants and commission earners, it would alter the calendar of cash flow that the Canada Revenue Agency (CRA), the federal tax collector, has imposed for years. It also arrives with less welcome detail: a new power for the CRA to report large unpaid tax debts to credit bureaus.
How the Once-a-Year Instalment Would Work
Under current rules, Canadians who owe tax that is not deducted at source, which describes most self-employed people, generally pay instalments every quarter. The budget’s tax measures annex proposes that individuals whose primary source of income is a business, including professional or commission income, be allowed to make one tax instalment instead. The payment would equal two-thirds of their combined federal-provincial net tax owing for the year and fall due by 31 December. The remainder would be due on the normal balance-due date.
The model already exists. Farmers and fishers whose chief source of income is farming or fishing can currently make a single instalment of two-thirds of net tax owing by 31 December, and the budget describes the new measure as extending similar treatment to other business income. It would apply to the 2028 and subsequent taxation years, so nobody’s payment calendar changes before then, and the measure still needs legislation to become law.
For a small business owner the practical effect is on working capital. Money that would otherwise have gone to the CRA in three earlier quarterly payments could stay in the business account for most of the year, with a larger single payment due at the end of December. That suits firms with seasonal or uneven income, though it also concentrates the bill into one month that already carries holiday wages, year-end supplier invoices and, for many retailers, peak stock costs.
Fewer Owners Would Need to Pay Instalments at All
The budget also raises the point at which instalments are required in the first place. The threshold would rise from C$3,000 to C$7,500 of net tax owing for corporations and for individuals resident outside Quebec, and from C$1,800 to C$4,500 for individuals resident in Quebec. The thresholds would be indexed to inflation and rounded to the nearest C$500.
The test would continue to look backwards as well as at the current year. Instalments would be required only where the relevant threshold is exceeded for the current year and for either of the two previous years. The higher thresholds would apply to taxation years beginning on or after 1 January 2028. In combination with the single annual tax instalment, that could take some smaller sole traders out of the instalment system altogether and give the rest a simpler one.
One Filing Date for Everyone, and a Year to Object
Two deadline changes land earlier. Today most individuals must file their T1 personal tax return and pay any balance by 30 April. Self-employed individuals and their spouses or common-law partners have until 15 June to file, although any balance owing is still due by 30 April. The budget proposes a single date of 15 May for both filing and payment for all individuals, including the self-employed, from the 2027 tax year.
That is a trade-off rather than a straight gain for business owners. They would get two extra weeks to pay, but they would lose a month of filing time, which matters for anyone whose accounts depend on year-end figures from clients, platforms or an accountant’s queue. Firms that currently file in June should expect to bring that work forward.
Disputes get more breathing room. Taxpayers generally have 90 days after a notice of assessment to file a notice of objection. The budget proposes one year for most taxpayers, and for individuals the later of one year after the notice is sent and two years from the filing due date. The trade-off here is that the ability to apply for an extension would be removed: miss the new deadline and the door closes. The change would apply to assessments sent on or after the day that is three months after royal assent.
Tax Debts Over C$50,000 Could Reach the Credit Bureaus
The measure most likely to catch owners off guard is a new disclosure power. The budget proposes amending the Income Tax Act to let the CRA tell credit bureaus about a taxpayer’s tax debts, under four conditions set out in the annex. The outstanding debt must exceed C$50,000. The assessments behind it must not be under objection or appeal, with all rights of objection and appeal expired. The CRA must have notified the taxpayer in writing at least 30 days before disclosing. And it must have taken reasonable steps to collect the debt and offered the chance to agree a reasonable repayment arrangement.
For a business that funds itself partly on personal credit, as many very small firms do, a tax debt appearing on a credit file could affect overdraft limits, card limits and lease applications. The safeguards mean it should not surprise anyone who is engaging with the CRA, but owners who have been leaving assessments unanswered would have a new reason to respond. The measure would apply on royal assent of the enacting legislation, according to the annex, and law firm Borden Ladner Gervais lists it among the CRA administrative changes in the package.
A C$15 Million Exemption for People Who Back Growing Firms
For owners who plan to raise money or sell, the headline business measure is the new Canada Growth Incentive. It would let a Canadian-resident individual claim a capital gains exemption of up to C$15 million on qualifying shares, a limit that applies separately to each individual for each business. According to EY’s summary of the budget, the shares must be issued by a Canadian-controlled private corporation whose combined assets, with related companies, do not exceed C$100 million, must be issued for cash or for employment services, and must be held for at least 36 consecutive months. Shares issued on or after 5 November 2026 and before 2037 qualify.
The exclusions are long. Professional practices, consulting and businesses that depend on the reputation or skill of employees are out, as are agriculture, fishing, forestry, mining, financial services, insurance, utilities, real estate, food and accommodation, arts, recreation and entertainment, and franchised businesses. Gains exempted this way would be subject to a 30% inclusion rate for alternative minimum tax, and claiming the exemption would limit an individual’s use of the existing lifetime capital gains exemption on shares of the same corporation. The government’s annex puts the cost at C$80 million in 2029-30 and C$485 million in 2030-31.
Founders who sell and reinvest also get more time. The rollover that lets an investor defer tax on gains from eligible small business shares when the proceeds go into another eligible small business would allow replacement shares to be bought until the end of the third calendar year after the sale, or up to five years where the investor signs an agreement for shares to be issued later, for dispositions from 1 January 2027. Separately, dividends paid by Canadian-controlled private corporations on or after budget day would be excluded from the Part VI.1 tax on taxable preferred shares, a technical regime whose removal, according to The Canadian Press, is meant to reduce administrative and compliance costs.
Why Small Business Groups Are Not Celebrating Yet
The government is selling the package as relief from paperwork. “Budget 2026 launches the most ambitious federal tax reform in decades. This generational initiative is about ensuring small and medium-sized businesses in Canada can spend less time and money on taxes and tax compliance and more time and resources growing their businesses and creating good jobs for Canadians,” Wayne Long, Secretary of State for the Canada Revenue Agency and Financial Institutions, said in a Department of Finance release on 13 November. Small and medium-sized businesses make up more than 98% of Canadian businesses, the release notes.
The main small business lobby was less impressed. “While there’s a mega deduction and there’s a focus on mega projects, my takeaway is that this is a mega disappointing budget for small business owners,” said Dan Kelly, president and chief executive of the Canadian Federation of Independent Business, according to The Canadian Press. Of the rollover changes, he said: “It already exists but they’re making it a little bit more flexible.” Hash Aboulhosn, chief growth officer at Merchant Growth, said: “There is a disconnect between the growth Ottawa wants to see and the reality for Canada’s small businesses. Many can’t afford to make those investments in the first place.” Randall Bartlett, deputy chief economist at Desjardins Group, expects a positive but modest effect on business investment. “The tax consideration is almost like the icing on the cake,” he said.
The politics remain contested. Conservative Leader Pierre Poilievre called it a “costly credit-card budget”, The Canadian Press reported, while Champagne has presented the plan, titled Masters of our Destiny, as a way to make Canada more resilient. For owners, the timetable matters more than the rhetoric: the filing date moves for the 2027 tax year, the instalment changes start in 2028, and none of it applies until the legislation passes. The budget’s investment write-off, the Productivity Mega Deduction, was set out earlier, and our analysis of how it halves Canada’s tax on new investment covers what it means for capital spending.
About The Author

More Stories
Five Green Steel Mills Are Racing to Replace Australia’s Imported Rebar
Why Small Firms Feel the Bank of England Rate Rise Twice
US GDP Grew 3.4% but Consumer Spending Stalled in September