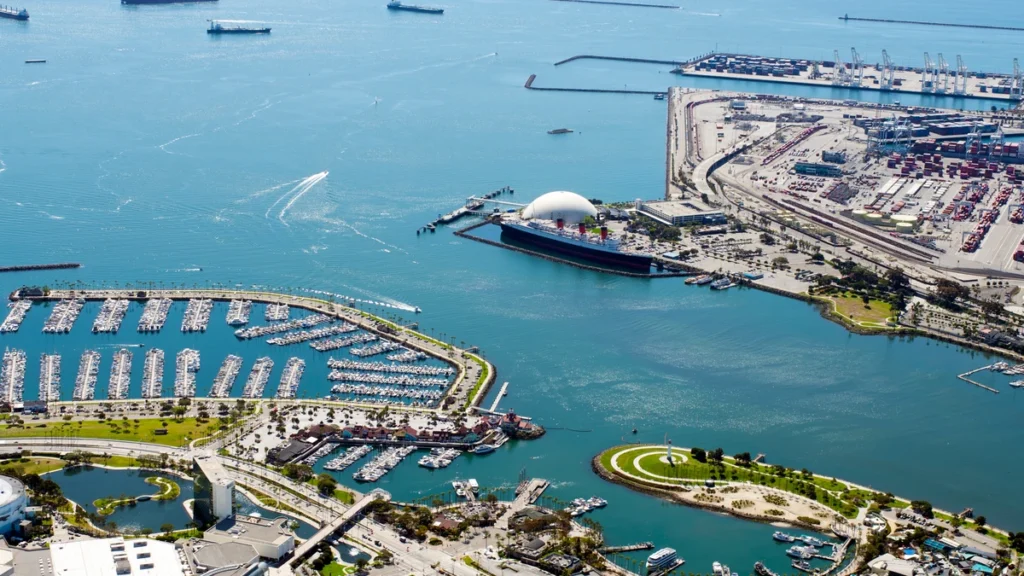
Long Beach, California, with the port container terminals at top right. Imports of capital goods, led by computers, subtracted from US growth in the third quarter.
Long Beach, California, with the port container terminals at top right. Imports of capital goods, led by computers, subtracted from US growth in the third quarter.
The US economy grew at an annual rate of 3.4% in the third quarter, up from 2.2% in the second, according to the advance estimate of US GDP published by the Bureau of Economic Analysis (BEA) on 29 October. The same statistical agency’s monthly accounts tell a less comfortable story about how the quarter ended: after adjusting for prices, American households barely increased their spending in September, while consumer prices rose 0.5% in a single month.
For business owners selling into the world’s largest economy, the two readings point in different directions. Demand across the summer was strong and broad, with companies buying equipment at a fast pace. The final month, though, showed stretched consumers, a low saving rate and inflation that has not finished its job, which is why the Federal Reserve held interest rates the day before the GDP release with two of its 12 voters arguing for a rise.
What the 3.4% Headline Actually Measures
US figures need translating for readers elsewhere. The BEA reports quarterly growth at an annualised rate, the pace the economy would expand if the quarter were repeated for a whole year. Measured the way the UK, Australia and New Zealand report it, as a plain change on the previous quarter, real US GDP rose 0.8% between April-June and July-September. Before adjusting for inflation, the economy’s output grew at an annual rate of 5.6%, according to an analysis of the release by MAS Economics.
The advance estimate is the first of three readings for each quarter, assembled before all the source data are in. The BEA’s release lists increases in investment, consumer spending and government spending as the contributors to growth, partly offset by a fall in exports, while imports, which are subtracted in the calculation, rose. The second estimate, published with corporate profits, is due on 25 November.
Economists often look first at a narrower line that strips out the most volatile pieces. Real final sales to private domestic purchasers, the sum of consumer spending and private fixed investment, grew at a 4.9% annual rate, slightly faster than the 4.6% of the second quarter. On that measure, demand from American households and businesses was not weak at all.
Inventories and Imports Nearly Cancelled Each Other Out
The parts of the quarter moved much more than the total. Businesses building up stock added 1.61 percentage points to growth, according to MAS Economics’ breakdown of the BEA contribution tables, with the BEA saying the inventory increase was led by wholesale trade and manufacturing, mainly in nondurable goods. Trade took away 3.32 points, the largest drag since the first quarter of 2025, with imports alone subtracting 2.64 points.
Consumer spending added about 2.5 points in both the second and third quarters, so households were not the source of the acceleration. What lifted the total from 2.2% to 3.4% was mostly government spending, whose contribution rose by 0.91 points, and business investment. Government spending added 0.90 points in total, nearly all of it federal: 0.41 points from defence and 0.49 from other federal spending. Housing subtracted 0.12 points.
Part of the federal increase is an accounting quirk. The national accounts treat sales of crude oil from the Strategic Petroleum Reserve, the government’s emergency stockpile, as negative government spending. Sales in the third quarter were smaller than in the second, which raises measured federal consumption, but the BEA notes that because the oil sold shows up elsewhere in GDP, there is no direct effect on the total.
The Computer Buying Behind the Investment Number
The most striking line sits inside business investment. The BEA says the rise in equipment spending was “led by information processing equipment (mainly computers and peripheral equipment)”, and MAS Economics calculates that equipment added 1.16 points to growth on its own. Fixed investment as a whole, the machines and buildings firms intend to use, added 1.66 points.
The same purchases explain much of the trade drag. According to the BEA, the largest contributor to imports was “capital goods, except automotive”, and exports fell, led by petroleum and related products. As MAS Economics puts it, American firms bought servers and computers at a fast pace and many of those machines were built abroad, so the same spending lifted the investment line and the import line together. For suppliers outside the US, that is the clearest signal in the release: corporate America is still spending heavily on computing capacity.
Consumers spent in familiar places. Within services, the BEA says the increase was led by health care, mainly hospitals and outpatient services, and by food services and accommodation. Within goods, the increase was led by other nondurable goods, mainly prescription drugs.
September Ended the Quarter on a Weaker Note
The BEA’s monthly income and spending report for September changes the texture of that picture. Personal income rose $54.5 billion, or 0.2%, mainly from wages and salaries and government social benefits led by Medicare. Spending in cash terms rose faster, by $113.1 billion or 0.5%, split between $35.1 billion on goods and $78.1 billion on services.
Once rising prices are taken out, almost nothing is left. Real personal consumption expenditures rose $2.6 billion in September, less than 0.1% at a monthly rate, which means the volume of goods and services households bought was essentially flat. MAS Economics calculates that real disposable income fell 0.3% in the month. The personal saving rate, saving as a share of income after tax, stood at 3.8%, a thin cushion if prices keep rising faster than pay.
A strong quarter that ends on a flat month tends to hand less momentum into the next one. That does not make the third quarter’s growth any less real, but it means October and November data will carry more weight than usual in deciding whether the summer pace held.
Inflation Cooled for the Quarter but Not for the Month
The quarterly and monthly price measures also diverge. Across the third quarter, the personal consumption expenditures (PCE) price index, the inflation gauge the Federal Reserve targets, rose at a 2.1% annual rate, down sharply from 5.0% in the second quarter. Excluding food and energy, it rose 2.5%, against 3.3%. The broader price index for gross domestic purchases rose 3.0%, compared with 5.6%.
September alone was hotter. The PCE price index rose 0.5% from August and 3.6% from September 2025. Excluding food and energy, prices rose 0.3% in the month and 3.1% over the year. Those annual rates remain well above the Fed’s 2% goal, which explains why a quarter of cooling inflation has not settled the argument on its rate-setting committee.
Why the Fed Held at 3.75% to 4%
On 28 October the Federal Open Market Committee, which sets US interest rates, kept the federal funds rate in a range of 3.75% to 4%, where it has been since a quarter-point increase in September. The statement was approved by a 10-2 vote. Governor Lisa Cook and Cleveland Fed President Beth Hammack dissented, both preferring to raise the range by a quarter of a percentage point.
The committee described economic activity as “expanding at a strong pace”, language CNBC noted was an upgrade from “solid” in September. It added that “domestic spending has been resilient” and that “capital investment is robust”, which matches the equipment numbers in the GDP release. On prices, the statement said: “Inflation remains elevated. The accumulation of more information will help the Committee determine the policy stance appropriate to ensure a timely return of inflation to the Committee’s 2 percent goal.”
The decision was widely expected, with markets pricing a less than 10% chance of a rise beforehand, according to CNBC. Futures pricing points to a strong possibility of another increase at the committee’s next meeting. Fed Vice Chair Philip Jefferson and New York Fed President John Williams have both said current conditions give policymakers time to judge their next move.
What Business Owners Should Watch Next
For companies trading with the US, the release carries three practical readings. Demand from American businesses for computers and other capital goods is strong enough to show up as a three-point drag from imports, the same hardware cycle that has left Micron unable to see the end of the memory shortage, as DailyBusiness.News reported in its look at the chipmaker’s results. Household demand was solid across the quarter but flat in its final month. And borrowing costs are more likely to rise than fall while annual inflation runs at 3.6%.
The calendar now matters. The BEA publishes its second estimate of third-quarter US GDP, together with October personal income and spending, on 25 November. Those figures will show whether September’s stall was a pause or the start of a slower patch, and they will be in hand before the Fed’s next rate decision on 9 December.
Until then, the advance estimate stands as a strong quarter with a soft finish: 3.4% annualised growth built on business investment and federal spending, real final private demand rising at 4.9%, and a September in which consumers held their spending steady while prices kept climbing.
About The Author


More Stories
The Gold Price Gave Back $1,570 an Ounce in Nine Months
Capping Commercial Credit Card Fees Saves NZ Firms $40m on Paper
LearnUpon Secured $50m Without Selling a Single Share