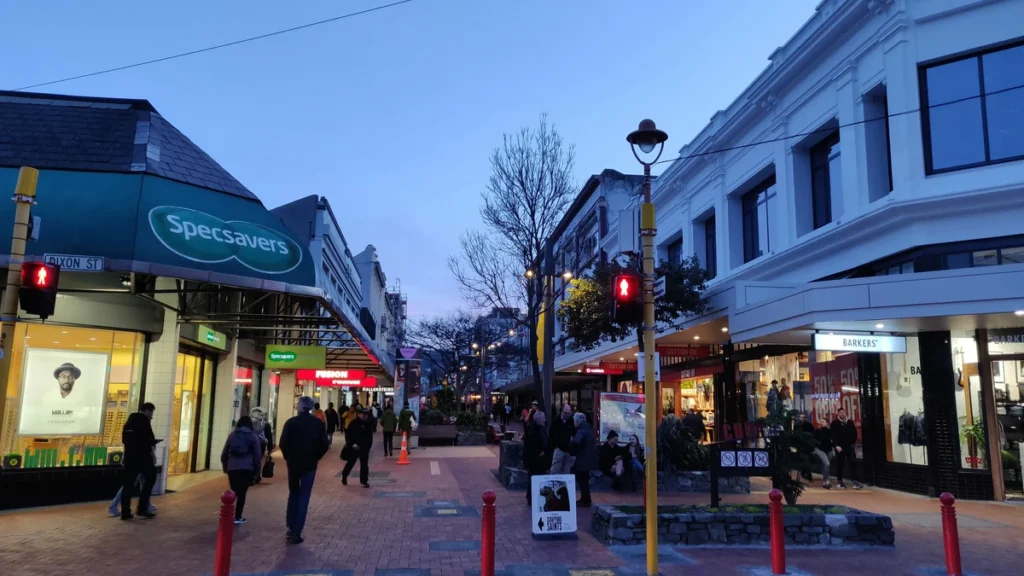
Shopfronts on Wellington's Cuba Street at dusk.
Shopfronts on Wellington's Cuba Street at dusk.
New Zealand businesses pay about NZ$170 million a year in merchant service fees to accept Mastercard and Visa commercial credit cards, and around NZ$125 million of that is interchange, the fee that moves between banks on every transaction. On 22 October the Commerce Commission, the country’s competition regulator, finalised a cap on that interchange from 22 April 2027 and put the saving for business at roughly NZ$40 million a year. Commercial credit card fees are the most expensive of any card a shop accepts, and from April they will be capped as well.
The NZ$40 million is a genuine estimate, but it is an estimate of a wholesale fee. Whether a cafe owner in Wellington or a builders’ merchant in Hamilton actually sees it depends on what happens between the cap and the monthly statement, and the regulator has limited power over that stretch.
What the Commerce Commission Decided
A commercial credit card is one issued to a business and typically handed to employees for work purchases. The Commission’s announcement explains that interchange is paid by the merchant’s acquirer, meaning the bank or payment provider that lets a business take card payments, to the card issuer for each transaction on the Mastercard and Visa networks. The acquirer then recovers it from the merchant inside the merchant service fee.
The final caps, according to law firm Buddle Findlay and B2B News, are 0.70% for in-person payments and 1.10% for online payments on domestic commercial credit cards, and 0.70% in person and 1.50% online on foreign-issued commercial cards. The current weighted average on domestic commercial credit cards is around 1.40%, interest.co.nz reported from the Commission’s reasons paper, which is more than double the rate on domestic personal credit cards and almost double Australia’s, near 0.8%.
The Commission puts the saving from this decision at about NZ$40 million a year. “This action, combined with earlier cuts to interchange fees on personal cards, should reduce businesses’ costs by around $290 million each year,” Commissioner Bryan Chapple said. The caps were set slightly higher than first proposed: a June draft had suggested a range between 0.5% and 1.5%, and the final domestic caps sit 0.2 percentage points above it, a change Buddle Findlay notes the Commission said did not alter its estimate of the impact.
Why Business Cards Cost Shops So Much
The economics are lopsided. Commercial credit cards make up 8% of the value of card transactions but 19% of all interchange fees paid, according to the Commission and Retail NZ, the industry body for retailers. The reason is what the fee pays for. “Commercial credit cards typically offer cardholders benefits like loyalty programmes, expense reporting, and interest-free credit, which are partially paid for by businesses through interchange fees,” Chapple said.
His point is that the cost does not stay with the business that accepts the card. “These fees ultimately flow through to retail prices, where everyone pays for benefits only some people receive, which creates an inefficient system,” he said. A shopper paying cash or by Eftpos, New Zealand’s domestic debit system, helps fund the rewards on a corporate card used two places ahead in the queue.
Shops also cannot see which card is which. “These credit cards attract the highest fees of all payment methods, yet retailers cannot tell at the point of sale whether the card someone is using is a personal, international or work card,” Retail NZ chief executive Carolyn Young said in a statement responding to the decision. The mix has shifted against merchants for years: Young told interest.co.nz that credit card transactions have risen from 44% to 72% of all transactions over the past decade, while Eftpos, which is free for merchants to accept, has declined sharply.
The Gap Between a Wholesale Cap and the Till
This is where the NZ$40 million becomes a figure on paper rather than a figure in the bank. The Commission regulates the wholesale interchange fee. It does not set the merchant service fee an acquirer charges a business, and it does not set the surcharge a business adds for customers who pay by card. Buddle Findlay notes that the Commission will monitor merchant service fees and conduct targeted reviews to check that savings flow through, which is oversight after the fact rather than a requirement to pass the cut on.
New Zealand has run this experiment before. After earlier caps on personal debit and credit cards, the Commission found in March 2026 that the average surcharge fell but the number of businesses surcharging actually rose, B2B News reported. Consumer NZ, the consumer advocacy group, has collected examples of a dairy (a corner shop) charging a 5% surcharge and a shuttle operator charging 6%. Consumer NZ’s Jessica Walker was sceptical about this round as well. “We would like to see some of the savings passed on to consumers. But we can’t see that happening,” she said.
Two leaks are possible, and they run in different directions. An acquirer can keep part of the interchange cut by leaving its merchant service fee where it is, which leaves the business no better off. A business can keep a cut that does reach it while leaving its surcharge unchanged, which leaves the customer no better off. Neither is unlawful, and the Commission’s monitoring is the only tool currently pointed at either one.
Retailers Wanted a Lower Number
Retail NZ backed a cap from the start and still supports this one, but it is unhappy about the number. “Retailers will feel let down by this decision, with commercial credit cards drawing the highest fees of any card accepted in store,” Young said. On the 0.2 percentage point difference from the draft, she said “that extra 0.2% would have made a real difference to retailers who accept these cards in store.”
Speaking to interest.co.nz, she was more measured. “The fees are a little higher than we anticipated, so that’s a little bit disappointing, but overall we support the cap on interchange fees,” she said. The body’s larger request is a different kind of rule altogether. “We have always said we’d like to see the total merchant service fee capped so we wouldn’t see other fees increase as a result,” Young said, describing card payments in New Zealand as “a true duopoly in terms of where and how people pay.”
The Card Schemes Make Their Case
The networks argue the fee pays for something real. David Peacock, Visa’s country manager for New Zealand and the Pacific Islands, told interest.co.nz that commercial credit cards play a “distinct role” in the economy, helping businesses manage cash flow, control spending and digitise procurement and payments. “It is important that regulatory settings preserve access to the tools businesses need while enabling continued investment in the security, fraud protections and innovation,” he said. Mastercard declined to comment to interest.co.nz.
The Commission’s own background note acknowledges that interchange exists in theory to balance costs and benefits between the issuing and acquiring sides of a card network, and that it can fund card credentials, anti-fraud measures, fraud losses, scheme fees, rewards and digital wallet fees. Its judgement is not that interchange should disappear but that, on commercial cards, it is “above efficient levels”. That is the disagreement in short: the schemes describe a service, and the regulator describes a price that has outrun it.
What Business Owners Can Do Before April
The Commission’s advice is practical. Businesses should review their merchant service fee arrangements and contact their payment providers to understand how the changes may affect their costs. In practice that means knowing whether a provider charges a single blended rate for all cards, in which case the cut may be invisible unless the blended rate is renegotiated, or a rate that separates out the card types, in which case the April change should show up on the statement.
It is also worth watching the alternatives. The Commission has estimated that open banking payments, which move money directly between bank accounts, could save businesses around NZ$180 million a year, interest.co.nz reported. Young called open banking a payments “middle ground”, while noting that the challenge is creating demand from consumers and merchants at the same time. For a business with thin margins, the most useful step before 22 April may simply be to check which payment types its customers use most, and what each one actually costs.
The Real Test Comes After 22 April
For New Zealand retailers, card fees are one fixed cost among several that have been squeezed into the open this year. DailyBusiness.News has reported on how the ratchet clause keeping NZ shop rents high became a political fight, and the logic here is similar: a cost that businesses could not negotiate on their own is now being set by policy instead.
The decision on commercial credit card fees settles the wholesale price. It does not settle what businesses pay their providers or what customers pay at the counter. The figure to watch after April is not the NZ$40 million estimate but the merchant service fee lines on business statements and the surcharge notices beside shop tills, which will show whether the saving moved from paper to practice.
About The Author


More Stories
LearnUpon Secured $50m Without Selling a Single Share
La Cordée Is Closing With $13 Million Owed and 210 Jobs Lost
Pensioners Would Carry Half the Private Health Insurance Rebate Cut