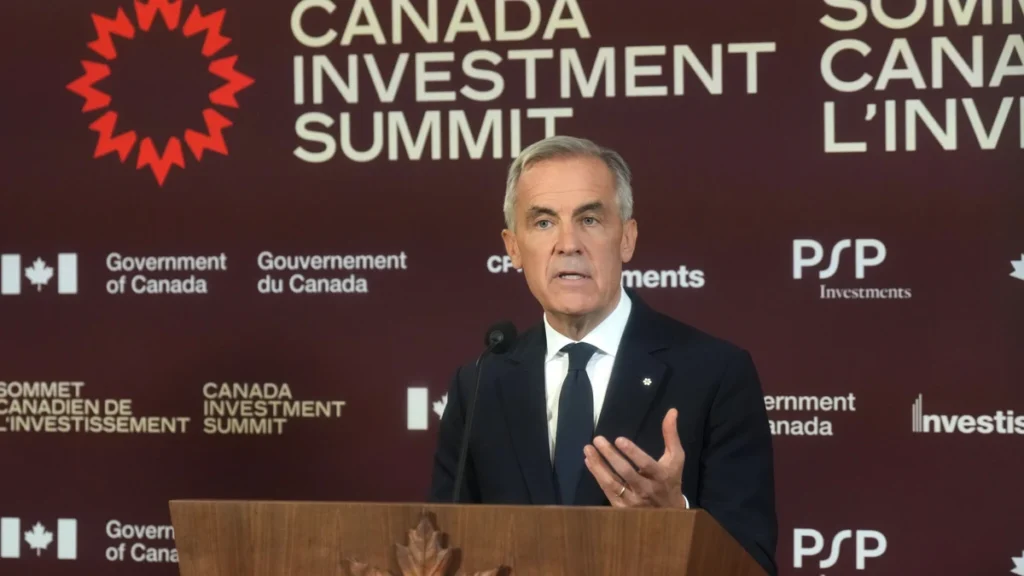
Canada’s tax rate on new business investment is set to fall by half. Under the Productivity Mega Deduction, announced by Prime Minister Mark Carney on 15 September at the first Canada Investment Summit in Toronto, companies would be able to deduct the full cost of most new equipment, software and infrastructure in the year it goes into use, and to do so permanently. The Department of Finance estimates that the change cuts Canada’s marginal effective tax rate on new investment from 13.0 per cent to 6.4 per cent.
That rate is the measure economists use to compare how much tax a country takes from the return on a new investment, and on the government’s own figures Canada’s would become the lowest of any major economy. The measure carries an estimated cost of C$36 billion over five years, and it applies to qualifying property acquired on or after 15 September 2026, according to the Department of Finance backgrounder. Draft legislative proposals were published alongside the announcement.
What the Productivity Mega Deduction Changes
Canada taxes business assets through capital cost allowance, or CCA, its system of tax depreciation. Normally a company that buys a machine or a server deducts its cost gradually over several years, at rates set by the asset’s CCA class. Immediate expensing collapses that schedule into a single year. In the Finance department’s words, it “allows taxpayers to fully write off the cost of an investment in the year that it becomes available for use.”
The idea is not new. Budget 2025 introduced a narrower Productivity Super-Deduction, which let firms deduct 100 per cent of eligible machinery, equipment and technology straight away. The Productivity Mega Deduction widens the net dramatically. According to the Prime Minister’s announcement, the share of assets covered rises from roughly 15 per cent to more than 65 per cent, and the eligible list now runs to fibre-optic cable, mining property, oil and gas pipelines, software, research and development, computer equipment, aircraft and vehicles, patents, rail track, bridges and roads.
Two features matter most for planning. The first is permanence: the backgrounder describes immediate expensing for a broad range of depreciable property “on a permanent basis”, rather than as a temporary incentive with a sunset date. The second is timing. Property has to be acquired on or after 15 September 2026, and the write-off is taken in the year the asset becomes available for use, so the date an asset is ready to be used, and not only the date it is paid for, decides which tax year benefits.
What Is Left Out of the Deduction
The exclusions matter as much as the headline. Buildings and additions to buildings in CCA classes 1 and 3 are out, as are franchises, licences and goodwill in classes 14 and 14.1, regulated natural gas distribution pipelines in class 51, certain vehicles in classes 10 and 10.1, and property depreciated under Schedules V and VI of the Income Tax Regulations, according to the backgrounder.
That leaves some assets on older rules. Manufacturing and processing buildings are excluded because they sit in class 1, but they keep the temporary immediate expensing announced in Budget 2025. Property that does not qualify for the new deduction remains eligible for the existing Accelerated Investment Incentive, a temporary measure that enhances first-year depreciation. Liquefaction equipment used in liquefied natural gas facilities, in class 47, is handled separately and qualifies for immediate expensing on assets acquired on or after 4 November 2025.
For a business with a mixed project, such as a new plant with a building, production lines and software, the result is that one investment can straddle three regimes: immediate expensing for the equipment and software, the temporary Budget 2025 regime for the manufacturing building, and the Accelerated Investment Incentive or regular capital cost allowance for anything that falls outside both.
The Numbers Behind the 6.4 Per Cent Rate
The government’s case rests on a sequence of cuts. Accelerated capital cost allowance measures in Budget 2025 reduced Canada’s marginal effective tax rate from 15.4 per cent to 13.0 per cent, according to Finance, and the Productivity Mega Deduction takes it to 6.4 per cent. For comparison, the department puts the US rate at 16.9 per cent and the OECD average at 19.0 per cent in 2026.
The costs and projected payoffs are both large. Finance puts the incremental fiscal cost at C$36 billion over five years from 2026-27, or around C$8.5 billion a year in average investment support. It projects that economic activity could rise by between 1.4 and 3 times the federal cost, an average of up to around C$22 billion in annual output, and it estimates long-term employment gains of up to 80,000 jobs a year ten years from now. These are the government’s own projections, and they depend on how much additional investment the incentive actually draws in rather than simply rewarding spending that would have happened anyway.
Carney presented the measure as a message to foreign capital. “With the lowest marginal effective tax rate in the G7 by an order of magnitude, we are sending a clear message to the world: Canada is building big,” he said in the announcement.
The Summit Behind the Announcement
The timing was deliberate. The deduction was unveiled at the first Canada Investment Summit, hosted by the federal government with CPP Investments and PSP Investments, two of the country’s largest pension investors. According to the Prime Minister’s Office, the summit brought together investors from nearly 30 countries managing more than $100 trillion in assets and produced nearly $500 billion in new investment commitments to Canada.
Several of those commitments came from Canadian institutions. CPP Investments and Brookfield Asset Management launched a $50 billion Maple Fund for infrastructure and strategic industries, PSP Investments said it would add $25 billion in Canada, TD Bank pledged $150 billion in financing over five years, and Bell Canada announced a $52.5 billion AI infrastructure hub in Saskatchewan with the provincial government. In principle, the tax change makes projects of that kind cheaper to carry in their early years, because the write-off arrives when cash flow is usually weakest.
Faster Tax Rulings for Billion-Dollar Projects
On 14 September, a day before the deduction was announced, the Canada Revenue Agency (CRA), the federal tax authority, added a second incentive aimed at the largest investors. Finance and National Revenue Minister François-Philippe Champagne announced that the CRA will prioritise advance income tax ruling requests linked to investments of C$1 billion or more in Canada, with immediate effect, according to the CRA’s announcement.
An advance ruling gives an investor a binding confirmation of how the Income Tax Act will apply before a transaction goes ahead, which the agency describes as “the highest level of tax certainty available from the CRA.” Other requests keep the existing 90-business-day service standard, which the CRA says was met for 91 per cent of rulings in the year to 31 March 2025. The program charges a cost-recovery fee of C$306.50 an hour, Advisor.ca reports.
Tax advisers welcomed the clarity but flagged the trade-off. Brian Ernewein, a senior adviser on national tax at KPMG in Ottawa, called the C$1 billion threshold an “easily applied metric”, but told Advisor.ca: “To my mind, it is the case that if you’re putting some [requests for advance tax rulings] ahead of others, then you’re putting some behind.” Fred O’Riordan of EY Canada said the agency would want “to maintain the capacity of that pipeline to deliver”, and described the move as “a very welcoming, business-friendly signal to these investors.”
Where Economists See Risk
Not everyone thinks the design is neutral between industries. In its round-up of expert reaction, The Hub cited Jack Mintz, President’s Fellow at the University of Calgary’s School of Public Policy, who has argued that “Given that investment is a long-term decision, temporary incentives have less appeal to companies,” a point in favour of making the deduction permanent. Mintz has also argued that a tax system tilted toward favoured industries misallocates capital and drags on productivity, and the list of exclusions means the benefit is uneven across sectors.
The Finance department’s own chart of sector-level rates after the Productivity Mega Deduction shows negative marginal effective tax rates in agriculture and fishing (-6.0 per cent), manufacturing and processing (-1.2 per cent) and transportation and storage (-2.3 per cent). A negative rate means the tax system would, in effect, subsidise the marginal investment in those industries. The Hub reported that the department acknowledges such rates could prompt over-investment in capacity, and its analysis noted that manufacturing already faced an effective rate near zero or below after the 2025 budget, while construction confronted a rate above 20 per cent.
That tension is the real policy question behind the headline number. A single low average rate is easy to sell to foreign investors, but the spread between sectors decides where the incentive actually bites, and buildings, the largest excluded category, sit outside it entirely.
What Canadian Businesses Should Check Now
For companies weighing capital spending, three practical points follow from the published material. First, the date: only property acquired on or after 15 September 2026 qualifies, and the write-off falls in the year the asset becomes available for use. Second, the asset class: buildings in classes 1 and 3, goodwill and certain vehicles remain outside the new rules, so a large project may be split across several regimes. Third, the legislation: the government has released draft proposals, and the final rules could still change before they are enacted.
None of this is a reason on its own to bring forward or delay a purchase, and the cash benefit arrives fastest for companies with taxable profits to set the deduction against. But for capital-heavy businesses in software, telecoms, mining, pipelines and transport equipment, the Productivity Mega Deduction changes the arithmetic of a new project from its first year. For a contrast in direction, DailyBusiness.News recently reported how capping salary sacrifice raises £468m a year from 2029 in the UK, a measure that adds revenue rather than giving it up to draw in investment.
About The Author

More Stories
The Whyalla Steelworks Furnace Went Cold and Took 600 Jobs With It
Government Borrowing Overshot the OBR by £3.5bn in One Month
Is the Bank of England One Meeting Away From a Rate Rise?