The UK government borrowed £18.3bn in August, according to the Office for National Statistics, which is £3.5bn more than the Office for Budget Responsibility had forecast for the month and £2.7bn more than City economists expected. It was the second-highest August on record in cash terms, behind only 2020, and it took government borrowing in the first five months of the financial year to £77.3bn, £8.1bn above the OBR’s path.
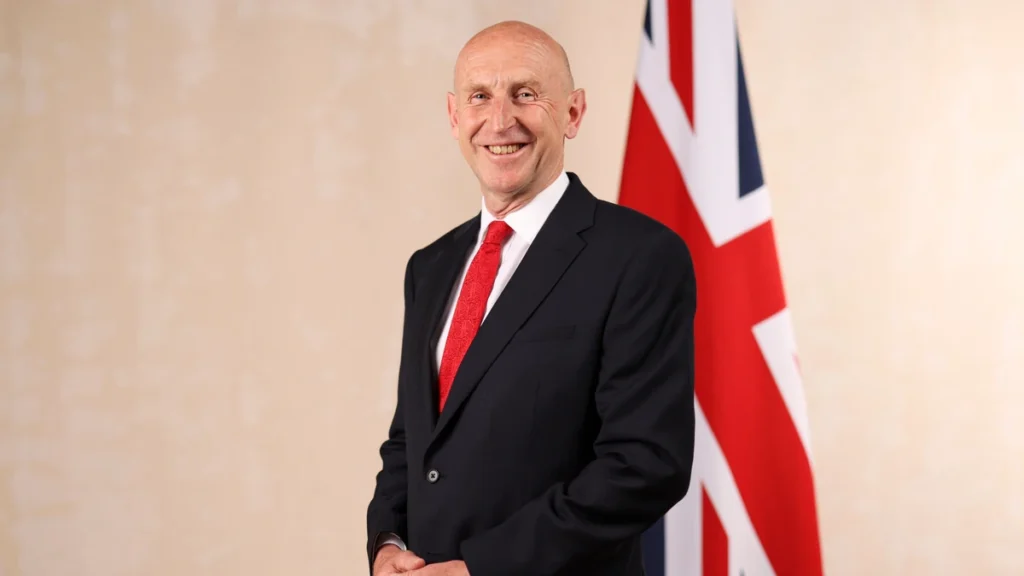
The timing matters as much as the size. John Healey delivers his first Budget as chancellor on 28 October, and the only borrowing release still to come before then, covering September, is due on 21 October. Every overshoot between now and then narrows the room he has to work with.
Where the £18.3bn Came From
The monthly gap was not caused by a fall in tax. Central government receipts rose 3.8% on a year earlier to £89.8bn, helped by a 6.6% increase in income-related taxes to £24.6bn. Corporation Tax brought in £8.6bn, up 4.7%. VAT grew more slowly, rising 1.7% to £17.6bn, and the ONS notes that the government’s Great British Summer Savings scheme cut the VAT rate from 20% to 5% on some family activities and children’s meals between 25 July and 1 September, at an estimated total cost of around £300m.
Spending simply grew faster. Total central government expenditure rose 5.0% to £103.1bn. Net social benefits climbed 6.9% to £29.2bn, which the ONS attributes largely to inflation-linked increases in many benefits and earnings-linked increases in the State Pension. Spending on goods and services, which includes public sector pay and the cost of delivering services, rose 5.7% to £39.8bn, and central government net investment was up 17.5% at £5.3bn.
Councils added to the pressure. Local government net borrowing was £4.5bn in August, up from £3.0bn a year earlier, an increase of almost half. Central government itself borrowed £13.3bn, £1.6bn more than in August 2025. Put together, the ONS summary is plain: spending growth outpaced the increase in receipts, partly because inflation pushes up both benefit payments and the cost of running public services.
An £8.8bn Interest Bill, and Why Inflation Drives It
Debt interest is the line most directly tied to financial markets, and it is the one that caught attention on the day. Central government interest payable was £8.8bn in August, up 5.3% on a year earlier. Business Matters reports that this was the highest August figure since equivalent records began in 1997.
Part of the explanation is specific to the way the UK borrows. A share of government debt is held in index-linked gilts, whose payments are uprated in line with the Retail Prices Index. The ONS notes that central government debt interest rises and falls with movements in RPI, which adds volatility to the monthly bill. Business Matters reports that RPI currently stands at 3.4%, and that City forecasts suggest it could breach 5% this year. If that happens, the interest bill rises automatically, with no new borrowing required.
The second channel is refinancing. “The higher [gilt] yields gradually feed through into a larger debt-interest bill as existing debt is refinanced,” said Martin Beck, chief economist at WPI Strategy, who described the figures as an “unwelcome setback” for the chancellor. Gilts that mature have to be replaced at today’s rates rather than the rates of the year they were issued, which is why a period of higher yields feeds into the bill gradually rather than all at once. Beck also noted that the government faces pressure to provide further cost-of-living support and to spend more on defence.
Why the Year So Far Looks Better Than It Is
On one measure the public finances are improving. Borrowing of £77.3bn in the financial year to August was £2.2bn, or 2.7%, lower than in the same period of 2025. As a share of the economy it came to 2.5% of GDP, which the ONS says is the 10th-lowest April-to-August total since comparable monthly records began in 1993.
The comparison that matters for policy, though, is against the forecast rather than against last year. The £77.3bn is £8.1bn above what the OBR projected in its March 2026 Economic and fiscal outlook. The current budget deficit, which covers day-to-day spending rather than investment, reached £51.9bn over the same five months, £4.8bn more than forecast. July had already surprised: Business Matters notes that the OBR expected a small surplus that month, and borrowing came in at £1.8bn instead.
Self-assessed Income Tax, an important summer receipt, was close to plan but not ahead of it. Receipts for July and August combined were £18.6bn, £1.9bn more than a year earlier but £0.4bn less than the OBR had forecast. “Borrowing in the financial year so far was lower than over the same period last year. However, it was higher than the official forecast, largely because central government borrowed more than anticipated,” said Tom Davies, senior statistician at the ONS.
Debt Sits Just Below £3tn
Public sector net debt was provisionally estimated at £2,985.5bn at the end of August, £78.5bn more than a year earlier. Measured against the size of the economy it was 93.8% of GDP, 1.3 percentage points lower than a year before but still at levels last seen in the early 1960s.
The wider balance-sheet measure, public sector net financial liabilities, which counts additional assets as well as liabilities, stood at £2,620.4bn, or 82.3% of GDP. One figure moved the other way in August. The central government net cash requirement, which measures the additional cash the government must raise from financial markets, was £10.0bn, £1.1bn lower than a year earlier and £2.0bn below the OBR’s forecast. Cash and accruals measures often diverge month to month, so a single month’s cash figure does not offset the borrowing overshoot, but it is a reminder that the monthly data rarely points in only one direction.
Five Weeks to the Budget
The overshoot feeds straight into the Budget arithmetic. Business Matters reports that the chancellor had £23.6bn of headroom against the government’s fiscal target, and that a rise in UK borrowing costs since the Iran war broke out has eroded it, with the headroom now estimated at between £10bn and £12bn following reports that Healey faces a £10bn gap. The chancellor has repeatedly said he will build a “buffer against uncertainty” into his plans and has warned of difficult decisions on tax and spending.
Economists read the August figures in that light. “Another round of tax rises in October now looks inevitable,” said Thomas Pugh, chief economist at RSM UK. James Smith, chief economist at the Resolution Foundation, said Healey “cannot afford to squeak through the budget with reduced headroom that gives him little buffer against fresh shocks”, adding that any support for families should be “carefully targeted towards those that need it most”.
The Treasury’s response was brief. Emma Reynolds, chief secretary to the Treasury, said the government was “committed to meeting our fiscal rules with a buffer against uncertainty”. She added: “At a time when debt interest costs billions of pounds that could otherwise be spent on improving lives, we must always know where the money is coming from to pay for public services.”
What Business Should Watch Before 28 October
For companies the practical question is less the monthly number than what the chancellor does with it. Several indicators point in the same direction. S&P Global’s flash purchasing managers’ survey, published on 23 September, showed the composite index falling to 51.7 from 52.5, and Chris Williamson, chief business economist at S&P Global Market Intelligence, said growth, confidence and employment were “hamstrung” by high energy prices, elevated business costs, geopolitical worries, higher market borrowing costs and uncertainty over government policy in the run-up to the Budget. Business groups are lobbying hard, and the CBI has warned that £345bn in business costs are holding back investment.
Borrowing costs are the thread connecting all of it. Our recent report on how gilt yields hit an eighteen-year high explained why the ten-year yield now sets the risk-free rate against which every sterling corporate borrowing decision is priced. The same yields that raise the government’s interest bill also set the benchmark for company loans, so the pressure on the Treasury and the pressure on a finance director’s refinancing plan come from the same place.
Two dates frame the next five weeks. On 21 October the ONS publishes September’s figures, the last before the Budget and the final test of whether the summer overshoot is a trend or a blip. On 28 October the chancellor sets out how he intends to close the gap, and whether he chooses tax rises, spending restraint or a smaller buffer will decide who carries the cost of an £8.8bn monthly interest bill. The full release is available on GOV.UK.
About The Author


More Stories
Is the Bank of England One Meeting Away From a Rate Rise?
Late Payment Doubled and Small Firms Reached for Credit Cards
Half of US Seed and Series A Money Went to $100m Rounds