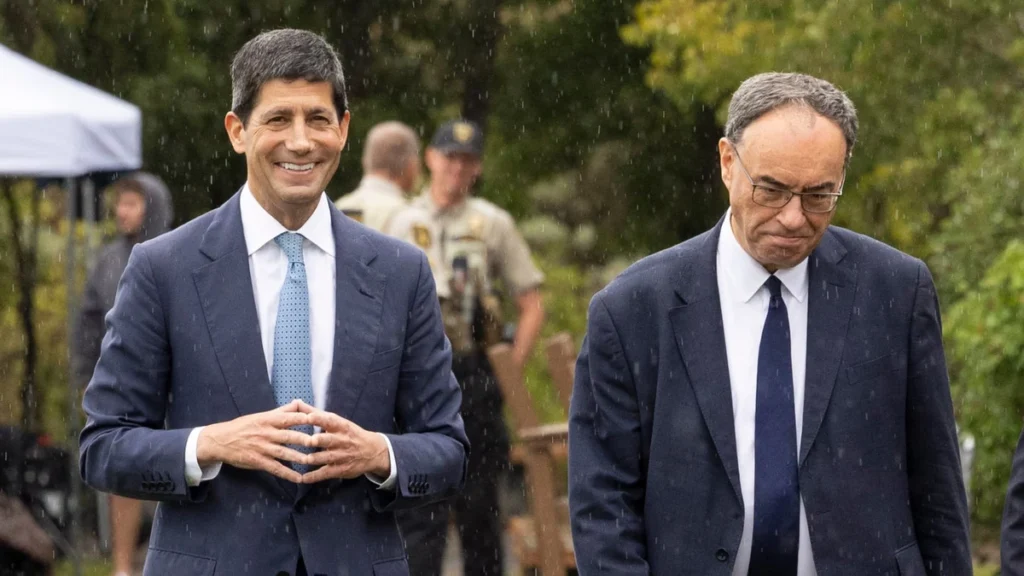
The Bank of England kept Bank Rate at 3.75% on Thursday 17 September, but it did so by a 6-3 vote and in language that reads like a warning. Three members of the Monetary Policy Committee wanted an immediate rise to 4%, the Bank now expects inflation to climb slightly above 4% in early 2027, and Governor Andrew Bailey said a rate rise becomes more likely the longer energy prices stay volatile.
The decision came a day after the US Federal Reserve raised its benchmark rate for the first time since July 2023. For UK firms that borrow, hire or set prices, the question is no longer whether the next move in Bank Rate is up, but how soon it arrives.
A Split Committee and a Sharper Tone
According to the Monetary Policy Summary and minutes, Andrew Bailey, Sarah Breeden, Swati Dhingra, Clare Lombardelli, Dave Ramsden and Alan Taylor voted to hold. Megan Greene, Catherine L Mann and Huw Pill voted for a quarter-point increase, the same three-way dissent the committee recorded in July.
What changed was the majority’s language. The committee said the risks to the inflation outlook were tilted to the upside, and more so than when it published its July forecasts. The minutes also recorded the view that, given how long second-round effects take to appear, it was not appropriate to wait too long for evidence of them before responding. Reuters, in a report carried by Business Recorder, noted that Bailey and his deputies Breeden, Lombardelli and Ramsden all raised the prospect of increasing Bank Rate in future.
Two members of the majority, Dhingra and Taylor, placed more weight on the slack in the economy, restrained pass-through of costs into prices and the already restrictive level of rates, arguing that these factors allowed time to gather more evidence. That split inside the majority is worth watching, because it tells businesses which data points could still hold the committee back.
Why the Dissenters Wanted 4% Now
The three dissenters set out their reasoning in the minutes and in individual statements reported by CNBC. Mann argued that raising Bank Rate is the better way to manage risk when the dynamics of inflation and its second-round effects are uncertain, because it avoids a worse outcome in which inflation becomes embedded and needs even tighter policy later.
Greene pointed to uncertainty about second-round effects from the conflict, alongside supply constraints linked to artificial intelligence and the El Niño weather pattern as further sources of price pressure. Pill said a rise would have sent a clear signal of the committee’s commitment to price stability at a time of geopolitical conflict and noisy data.
The minutes add a timing argument that matters for employers. The dissenters noted that the projected surge in inflation would peak in early 2027, just as wage settlements for the year are agreed. If pay deals lock in higher inflation expectations, the Bank would face a more persistent problem than an energy spike alone.
The Energy Shock Behind the Forecast
The numbers in the minutes explain the shift. At the close of business on 14 September, Brent crude had reached $106 a barrel and UK wholesale gas 207 pence per therm, rises of 36% and 78% respectively since the period before the July forecasts. The prices of petrol, diesel and jet fuel had risen by broadly similar amounts.
CPI inflation rose to 3.1% in August, triggering an exchange of open letters between the Governor and the Chancellor. The Bank estimates that around 0.7 percentage points of the 1.1 point overshoot came directly from energy, mostly motor fuels. Services inflation was 3.4%, unchanged from July but down from 4.5% in March.
Based on energy prices on 14 September, the Bank now expects inflation of around 3.75% in the final quarter of 2026, up from 3.2% in its July forecast, and slightly above 4% in the first quarter of 2027. Ofgem’s price cap for October to December rises to £1,723, a little higher than the Bank had assumed, and the cap is expected to rise substantially further in early 2027.
There is some relief inside those figures. The indirect effect of energy on other prices has so far been smaller than feared. The Bank’s regional Agents now expect annual food inflation of around 4% at the end of 2026, compared with expectations of 6% to 7% back in April, although the Bank warned that drought in Europe and El Niño pose upside risks to food prices next year.
What It Means for Borrowing, Pay and Growth
For businesses, the pass-through from market rates to lending has been full and fast. The minutes note that the quoted rate on a two-year fixed-rate mortgage is around 95 basis points higher than before the conflict, and that the rates faced by households and businesses remain materially higher than they were. The market curve for short-term interest rates was upward sloping and peaked at around 4.9% by the end of 2027, even though most respondents to the Bank’s own survey of market participants had expected a prolonged hold.
Pay growth is cooling but not collapsing. Private sector regular pay growth was 2.9% in the three months to July, and the Bank judges underlying private sector wage growth to be around 3.5%. Firms responding to the Decision Maker Panel expect wage growth of 3.4% over the next year, a figure that has been stable since before the conflict began.
Activity has held up better than expected. GDP grew by 0.4% in the second quarter of 2026 and by 0.4% in July, and Reuters reported that the Bank raised its estimate for third-quarter growth to 0.4% from 0.1%. Stronger growth gives the committee less reason to fear that a rate rise would tip the economy into weakness.
Markets moved on the announcement. The pound fell by around half a cent against the dollar and gilt yields dropped, according to Reuters. Before the meeting, markets had priced a 76% chance of a hold, according to LSEG data cited by CNBC, with a rise of at least 25 basis points widely anticipated in November. Long-dated borrowing costs were already under pressure, as DailyBusiness.News reported when gilt yields hit an eighteen-year high at the start of the month.
The Gilt Sales Pause Nobody Expected
Alongside the rate decision, the committee voted unanimously to reduce its stock of gilts held for monetary policy purposes to zero through a multi-year plan, with the remaining holdings unwound at an average pace of £46 billion a year by the end of 2034, including sales of £20 billion a year alongside maturing gilts.
The surprise was in how the Bank will do it. Its market notice says £222 billion of gilts maturing before 2035 will be held to maturity, and £120 billion of the longest-dated gilts will be kept to back banknote issuance. For the £146 billion of gilts maturing between 2035 and 2049, the Bank is working with HM Treasury and the Debt Management Office on a model in which the Government would buy the bonds at market prices. The Bank will review progress before April 2027, and its gilt sale auctions are paused in the meantime. Reuters described the pause in active sales as unexpected.
The Fed Moved First, and So Did the ECB
The Bank of England’s hold leaves it out of step with its peers. On Wednesday the Federal Reserve voted 12-0 to raise its target range by a quarter point to 3.75%-4%, and its projections showed 16 of 18 participants expecting another rise this year, according to CNBC. Chairman Kevin Warsh said inflation had been too high for too long. Fed officials raised their projection for headline PCE inflation this year to 3.7% and do not expect to reach their target until 2029.
US markets took the move badly once Warsh began speaking. The Dow Jones Industrial Average fell 631.21 points, or 1.21%, to 51,461.90, the S&P 500 fell 0.45% and the 10-year Treasury yield moved back above 5%, according to CNBC’s market coverage. Bank shares fell on fears that higher rates would slow lending. CNBC also reported that the European Central Bank raised rates last week for the second time this year, and that the Bank of Japan was expected to raise its key rate on Friday.
What to Watch Before November
The next Bank of England decision is due on 5 November, alongside a full Monetary Policy Report. Aberdeen economist Felix Feather told Reuters that a meeting with new forecasts would be a natural starting point for a hiking cycle, while Suren Thiru of the Institute of Chartered Accountants in England and Wales said the risk of a rise had moved from a possibility to a probability.
Three dates matter for businesses before then. The Budget on 28 October will set the fiscal backdrop the committee has to weigh. Energy prices through October will decide whether the Bank’s projection of inflation above 4% holds or rises. And pay settlements agreed over the winter will show whether the second-round effects the dissenters fear are starting to appear.
None of this makes a rise in November certain. The committee has not moved Bank Rate since December, and two members of the majority still want more evidence. But on the Bank of England’s own numbers, the argument for waiting has become harder to make with each meeting.
About The Author


More Stories
Late Payment Doubled and Small Firms Reached for Credit Cards
Half of US Seed and Series A Money Went to $100m Rounds
PizzaExpress Closed 73 Sites and Now Wants a Thousand